- 📈 Luxury is the only segment on the rise · +5.2% in revenue per available room expected in 2026 in the luxury sector, +0.7% in the mid-scale, −0.6% in the economy sector (CBRE).
- 🧖 Wellness is no longer an amenity, it is the architecture of the stay · $1,100 billion today, $2,100 billion expected by 2030. Sleep tourism alone will jump from 93 to 149 billion.
- 🏠 Hotels are now selling real estate · 910 branded residence programmes at the end of 2025, compared with 764 a year earlier, and over 1,500 expected by 2030 (Savills).
- 🏷️ Conversion is outpacing construction · repositioning an existing hotel under a major brand is faster than building from scratch, and costs less.
- 🤖 AI has won over the back office and lost the front desk · 98% of hoteliers use it, but 59% believe reception should remain human.
- 🧹 The constraint is no longer demand, it is staff · 71% of hotels have unfilled vacancies, especially in housekeeping and reception.
A trend in the hotel industry cannot simply be decreed in January: it is proven by openings, acquisitions and the year’s figures. Here is where luxury hospitality truly stands at the end of 2026, what has changed over the past year, and what did not happen despite the announcements.
In a nutshell: at the end of 2026, luxury hospitality is the only hotel segment whose prices are rising, wellness has become the primary reason for stay rather than a perk, groups are now selling real estate just as much as nights, conversions are outpacing new builds, artificial intelligence is working behind the scenes without guests seeing it, summer maps are heading further north due to heatwaves, and the challenge is no longer finding guests but finding staff.
Eleven movements shape the current landscape. The first dictates all the others.
- 📊 RevPAR · revenue per available room. All room revenue generated, divided by the total number of rooms, including those left empty. A single figure that shows both whether a hotel is filling up and how much it is charging. It is the key indicator watched by the entire industry.
- 🏷️ Conversion · an existing hotel that keeps its walls and staff while changing brand to join a major group. The opposite of a new build.
- 🏠 Branded residences · apartments sold to private individuals within a hotel complex, branded and managed by the hotelier. Buyers purchase a home and palace-level service.
- 🏗️ Pipeline · announced rooms that are not yet open. A group’s order book and the best indicator of its market outlook.
Four figures to contextualise the end of 2026
Luxury is the only segment on the rise
This is the starting point, and it is far from obvious during a year of uncertainty. CBRE expects a 5.2% increase in revenue per available room in luxury for 2026, compared to 0.7% in the mid-scale and a 0.6% decline in the economy sector. At one end of the market prices are rising, at the other they are falling, and the gap is approaching six points.
This divergence dictates everything else. When only one segment holds its pricing, capital moves there, brands reposition themselves, and owners invest because it is the only place where spending yields returns. In the UK, £2.1 billion worth of hotels changed hands in the first half of 2026, including £1.4 billion in London. In Spain, €2.46 billion. Blackstone is preparing the stock market flotation of 61 Mediterranean resorts valued at up to €7 billion.
Why this gap dictates everything else
A qualification, however, for anyone reading this as global plain sailing: performance varies greatly by region. The Middle East became, within a single quarter, the worst-performing hotel market on the planet in revenue growth. Luxury is rising, but not everywhere nor at the same time.
Wellness has become the primary reason for travel
This is the most profound transformation, and its nature has changed. Hotel spas used to be an amenity, much like a swimming pool. They have become the reason for booking. Wellness tourism was valued at $1,100 billion and is expected to reach $2,100 billion by 2030.
From leisure spa to medical protocol
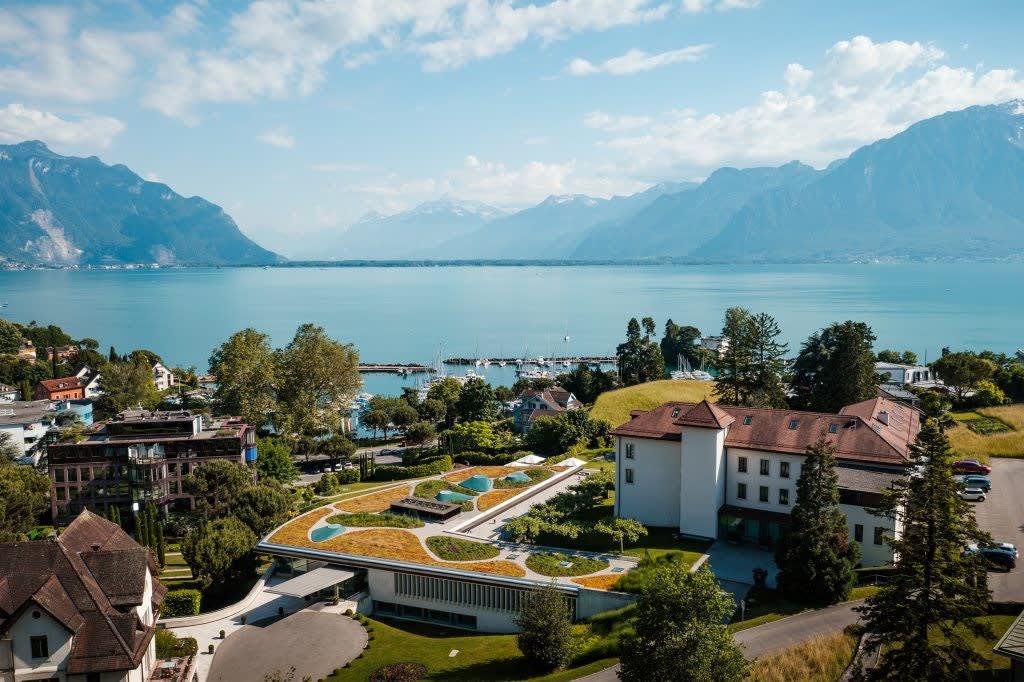
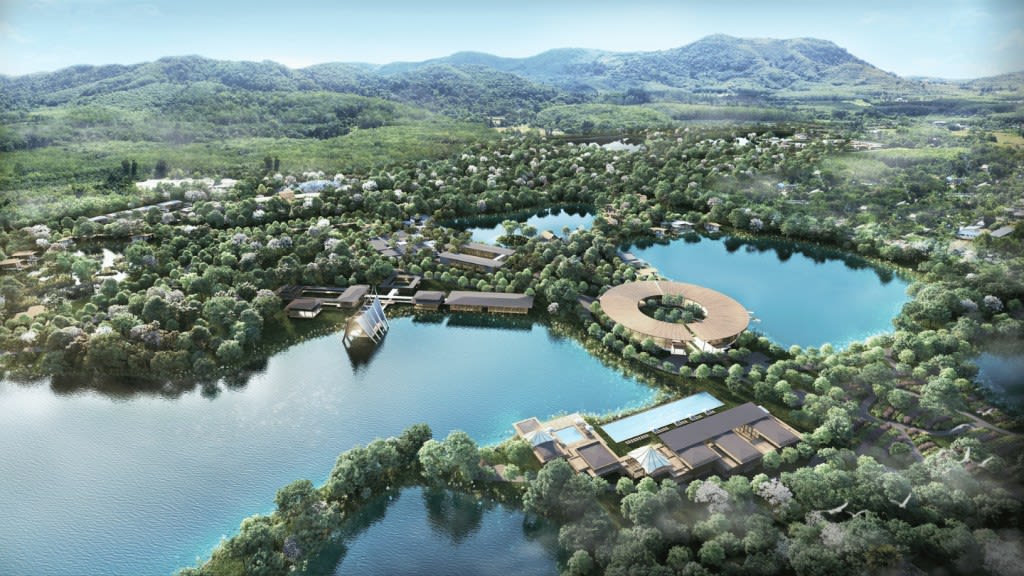
The vocabulary has evolved: biomarkers, genetic testing, multi-day protocols. Clinique La Prairie, which operates a hospital inside a hotel on the shores of Lake Geneva, is opening in Phuket in November 2026 and has announced Saudi Arabia for 2027. SHA Wellness is preparing an entire island in the Emirates combining a clinic, resort and 137 residences. Six Senses will open seven properties in 2027, with residences designed around nutrition, sleep and immersion in nature.
The signal: the cure has left the hotel
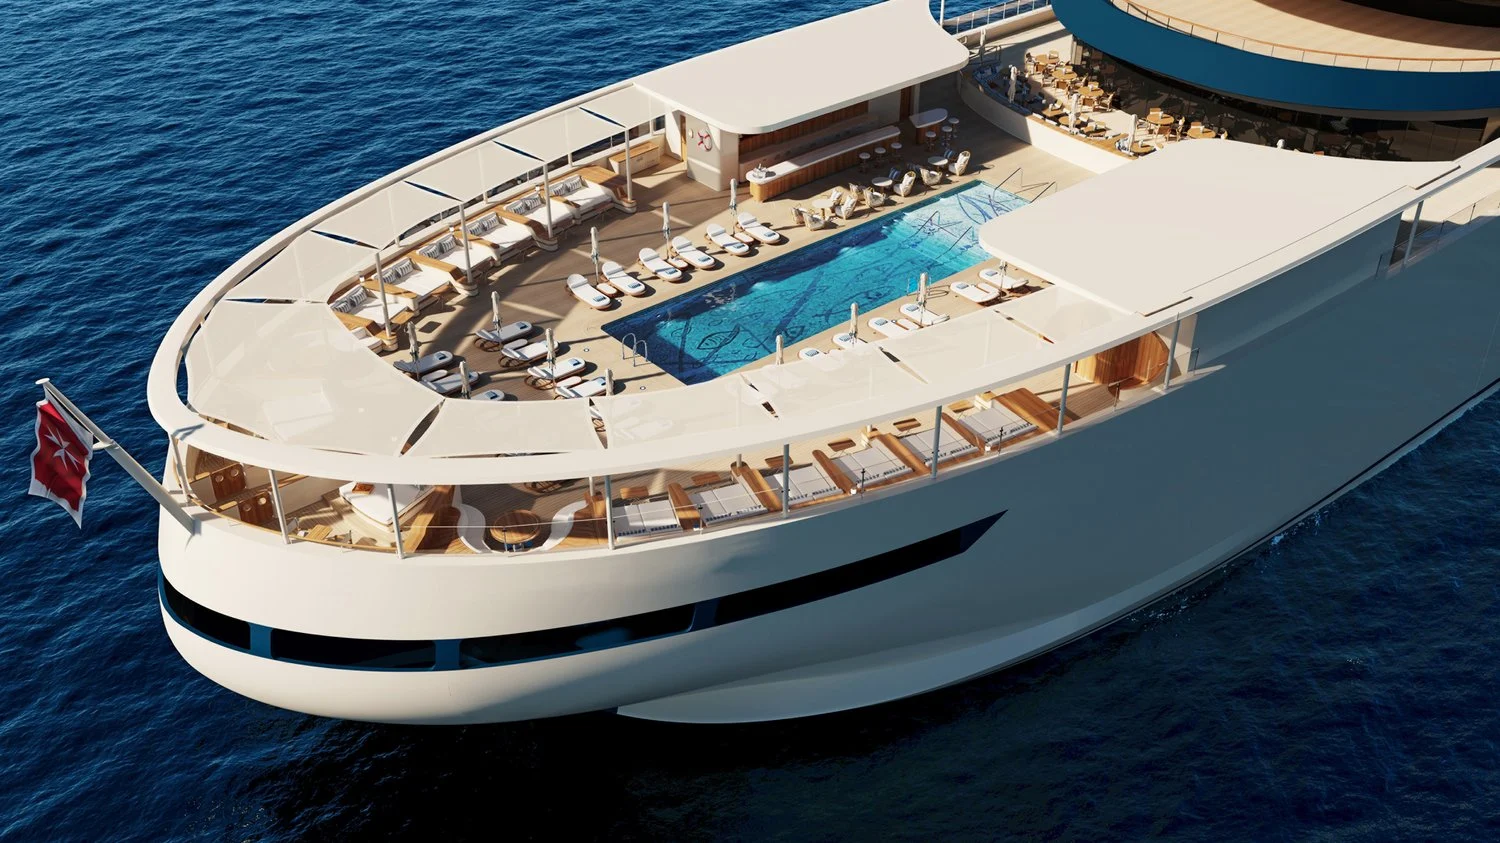
Yet the most telling shift is not a hotel. In September, the Four Seasons I yacht welcomed the Lanserhof clinic on board for an eight-day health cure during a transatlantic crossing. When a medical protocol boards a ship to occupy travel time, wellness no longer accompanies the stay: it has become its purpose.
A nuance is necessary, borne out by our own data. Looking at what hotels highlight across the 704 news pieces we have published since March, spas come first at 18.3%, ahead of dining and chefs at 13.2%, whereas the order was reversed a decade ago. However, three-quarters of these mentions still relate to traditional spas, and only 8.2% to longevity or medical wellness. Clinics are not the norm: they are the vanguard.
Our survey · what luxury hotels highlight
In-house tracking across 704 news stories published between March and September 2026. An article may cite multiple selling points.
Sleep is now a marketable product
This is the fastest-growing and most concrete branch of wellness. Sleep tourism is valued at $93 billion in 2026 and is expected to reach $149 billion by 2030, representing over 12% annual growth.
Major brands have industrialised the concept. Park Hyatt New York has installed Restorative Sleep Suites equipped with software-controlled beds that adjust pressure points throughout the night. Rosewood has rolled out its Alchemy of Sleep programme across twenty properties. Six Senses begins its retreats with a consultation with an in-house sleep doctor who designs a bespoke itinerary.
What is being sold here is not a room, but an outcome. This marks a fundamental shift for an industry whose product has always been space and a night’s lodging.
Silence has become a product
This is the logical extension of sleep, and arguably the year’s most distinct cultural shift. According to Hilton’s 2026 trend report, the primary motivation for travel is no longer discovery, but “resting and recharging”. Calm has overtaken curiosity.
When the industry invents a word for it
The sector has coined the term hushpitality to describe this hospitality of silence: tranquil environments, low-stimulation design, screen-free stays. Silence has become high-end currency, and it is engineered as such with enhanced acoustic insulation, vibration-absorbing materials and lighting that aligns with the body’s natural rhythms.
Some properties go further, treating the network itself as a nuisance: paint and wall coverings that block Wi-Fi and phone signals in rooms. Elsewhere, guests hand in their devices upon arrival in exchange for an offline programme featuring walking, sound baths, reading and creative writing workshops.
What this says about luxury itself
The change runs deeper than a passing trend. Luxury used to be measured by what was displayed; it is increasingly measured by what is felt. Privacy, slowness, silence and authenticity have become markers of prestige, whereas ostentation once was. This aligns with everything else in this article: if wellness is the purpose of the stay and sleep is a product, then noise is the defect to be eliminated.
Hotels are now selling real estate
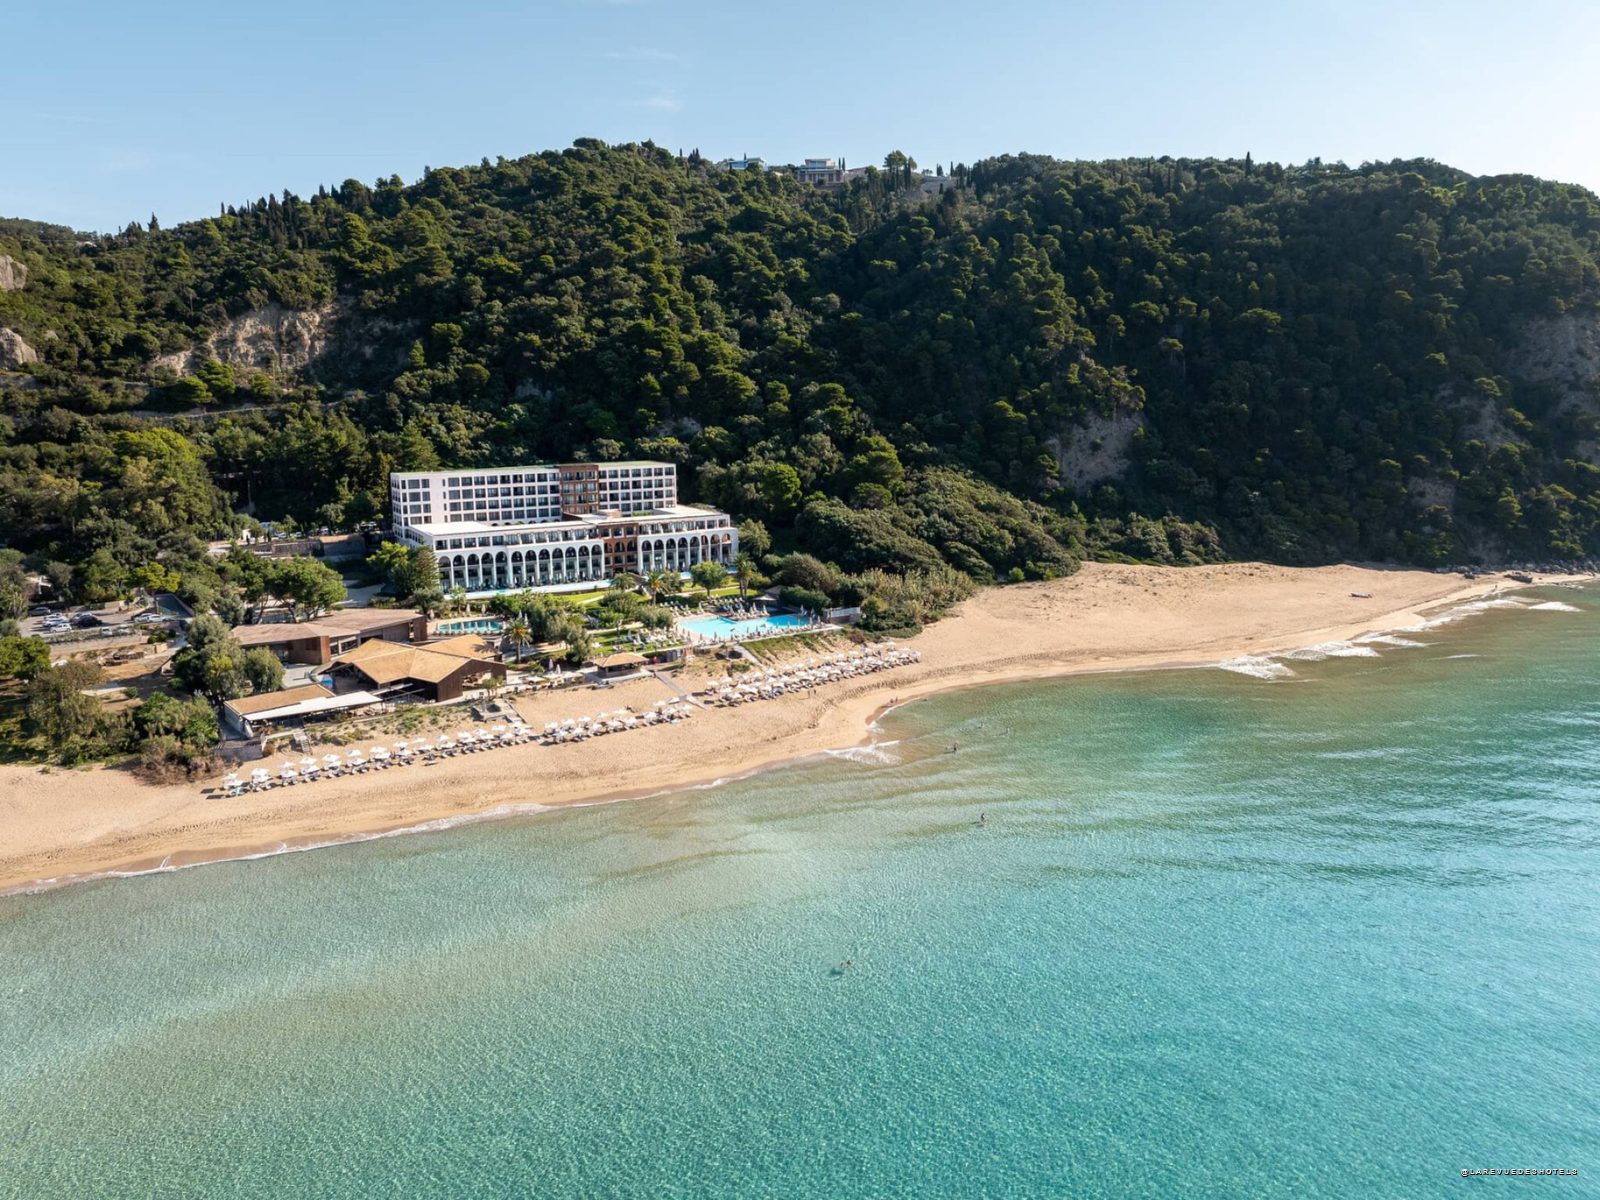
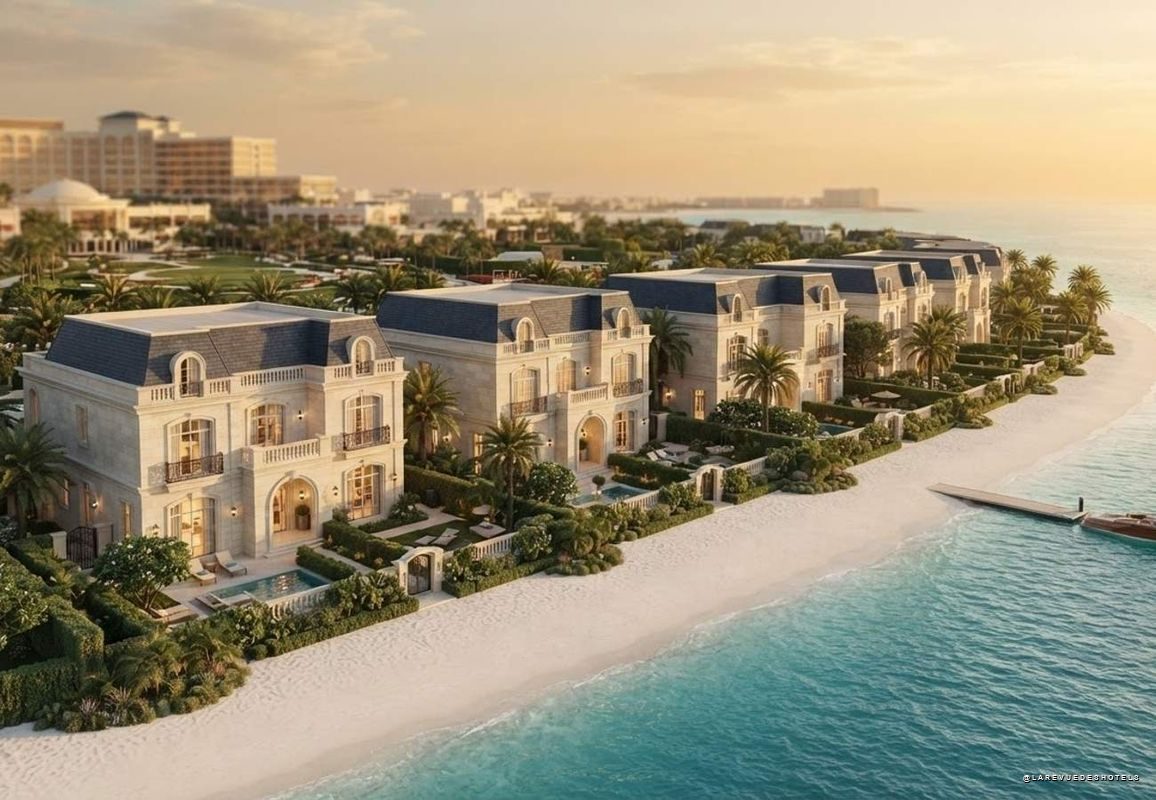
The movement is massive yet barely visible to the general public. The world boasted 910 branded residence programmes at the end of 2025, compared to 764 a year earlier, representing 19% growth in twelve months. Savills expects over 1,500 by 2030. The Middle East and Africa region shows the strongest five-year growth at 187%.
Why all groups are jumping on board
The principle is straightforward: hoteliers no longer just rent out nights, they sell apartments and subsequently charge for management and branding. For developers, the brand increases the price per square metre. For hoteliers, sales help finance construction. This has become one of the few financial structures that makes luxury projects viable, explaining a portion of the openings announced for 2029 and 2030.
Examples are multiplying: Wynn Al Marjan Island has unveiled 1,110 m² townhomes even before opening, and Hotel Emiliano will open in Brazil within a Foster + Partners development featuring 83 private residences.

Conversion is outpacing construction
When luxury is the only segment holding its pricing, it is faster to reposition an existing building under a major brand than to build a new one. The brand becomes an asset revaluation tool, and groups’ pipelines are filling up with pre-existing properties.
Three conversions that illustrate the method
Naples Grande Beach Resort will become a Signia by Hilton in January 2027, Oxford Witney Hotel will become the UK’s first JdV by Hyatt in late 2026, and London Bridge Hotel will join the Tapestry Collection by Hilton in 2028. None of these three are new builds.
The balance of power is clear: across our six months of tracking, there were 159 openings compared to 85 takeovers of existing properties, meaning one conversion or heavy refurbishment for every two inaugurations. Furthermore, the buyer profile has shifted. In the UK, owner-operators account for 40% of acquisitions, ahead of investment funds at 37%. These are hoteliers expanding, not just financiers allocating capital.
AI has won over the back office
This is the topic where the gap between rhetoric and reality is most fascinating, though not in the way people assume. Artificial intelligence is massively deployed: 98% of hoteliers surveyed in May 2026 report using it. It has simply settled where guests cannot see it.
Where artificial intelligence actually works
It sets prices: Hilton attributes a 5% to 8% revenue increase to its AI-driven segmentation, while citizenM reports an 18% increase in revenue per available room. It monitors buildings: Hilton’s LightStay platform has generated over $1 billion in verified savings while reducing the portfolio’s energy and water consumption by roughly 20%. It handles routine queries: conversational agents independently resolve 60% to 80% of repetitive questions.
And where the sector refused to let it go
Yet it stops at the front desk, and that is a deliberate choice. In the same survey, 59% of hoteliers believe that guest reception and check-in must remain managed by humans. The sector has decided without making a fuss: AI handles pricing, energy and messaging, but it does not shake hands. For a luxury guest, the only visible trace of this revolution will be better-adjusted pricing.
Where people are actually booking
A simple question, rarely asked in trend reports: where are travellers actually going? The answer contradicts much of the media noise.
Europe remains dominant
The world recorded 1.52 billion international arrivals in 2025, a record. And Europe alone captures 793 million of them, accounting for over half the planet. Asia-Pacific follows with 331 million, the Americas with 218 million, the Middle East with just 100 million, and Africa with 81 million.
International arrivals by continent, 2025
1.52 billion travellers in total. Year-on-year growth in brackets.
Source: UN Tourism. ⚠️ These figures count traveller arrivals, not hotel nights: they show market hierarchy, not exact hotel booking volumes.
But growth is elsewhere
Rankings by volume mask the underlying trend. Africa is growing the fastest at +8%, driven by North Africa at +11%. Asia-Pacific gains 6%, Europe 4%, the Middle East 3%, and the Americas manage just 1%.
Two interpretations emerge, pointing in opposite directions. Asia-Pacific remains 9% below its 2019 level, making it the only region yet to fully recover, and representing the greatest untapped potential. Conversely, the Middle East stands 39% higher than pre-2019 levels, an unprecedented surge which makes the collapse in its hotel revenues this quarter all the more striking.
Most visited countries · international arrivals 2025
Followed by China, Italy, Turkey, Mexico, Thailand, Germany and the United Kingdom.
At country level, France remains the world’s leading destination with 102 million arrivals, ahead of Spain with 96.8 million and the United States. It is the first country in history to surpass the hundred-million visitor threshold.
What this means for hoteliers
Early 2026 confirms the hierarchy without shaking it up: +4% in Europe in Q1, +3% in Asia-Pacific, +4% in Africa, for global growth of 2%. UN Tourism expects 1.58 billion arrivals over the year.
The conclusion is unsurprising yet robust: luxury is built where people are already going. The most high-profile announcements target regions that together account for less than 12% of global arrivals. Europe absorbs one traveller in two, which is precisely why capital has returned there.
The European map is shifting north
The previous section shows where the world is going. This one reveals what is shifting within Europe, and the movement is stark. It has a name: coolcationing, the deliberate choice to spend summer in a cool country rather than on an overheated coastline.
Figures rarely seen across a single season
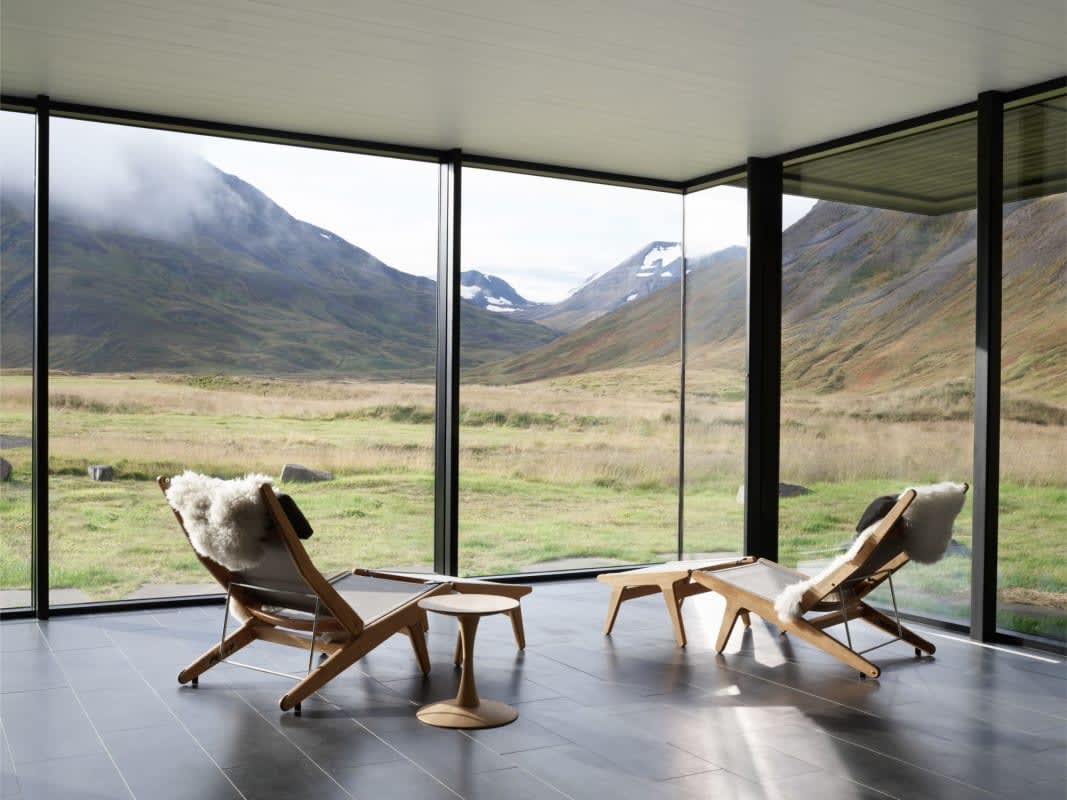
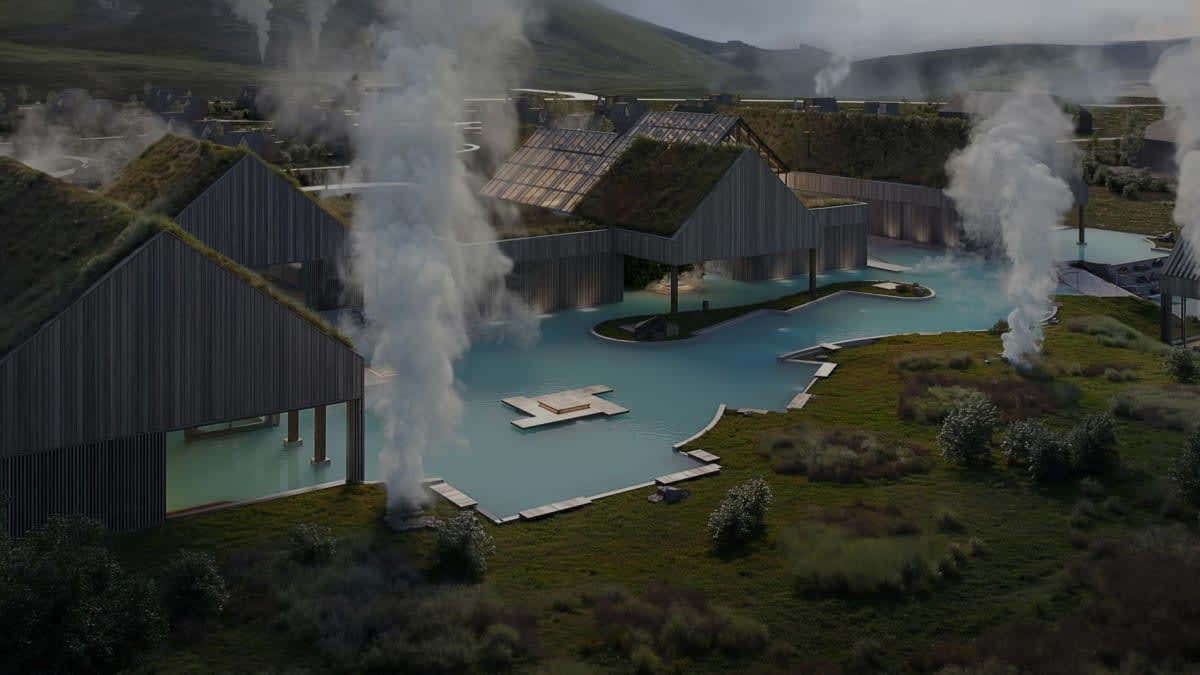
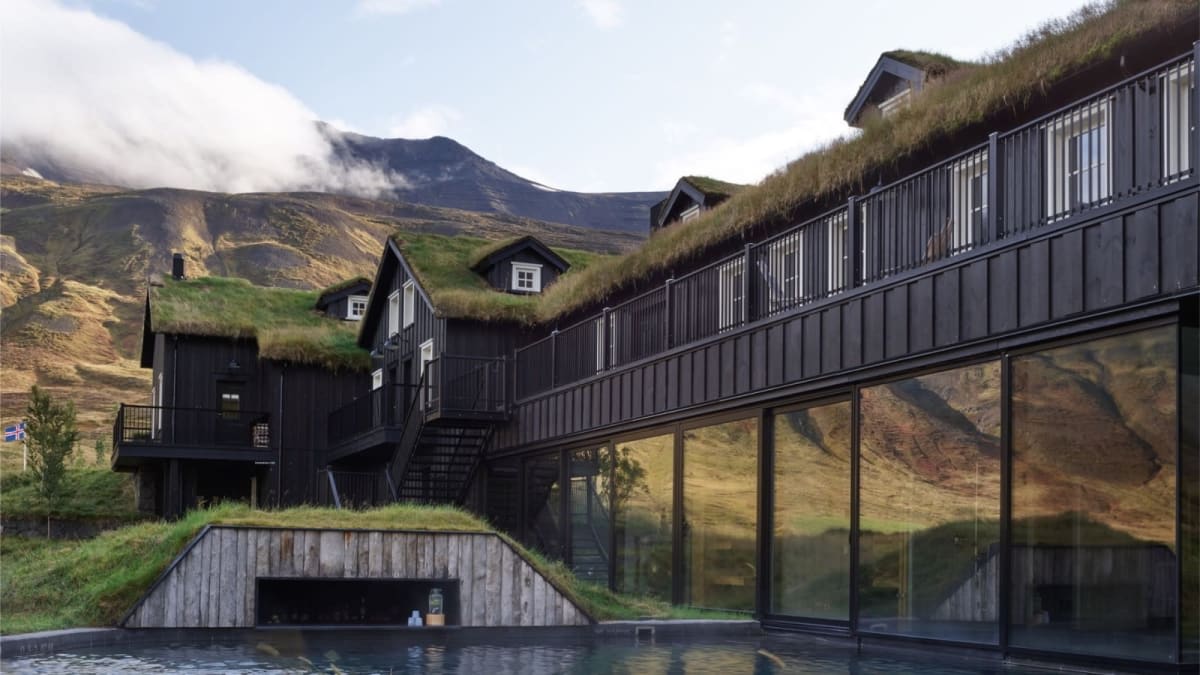
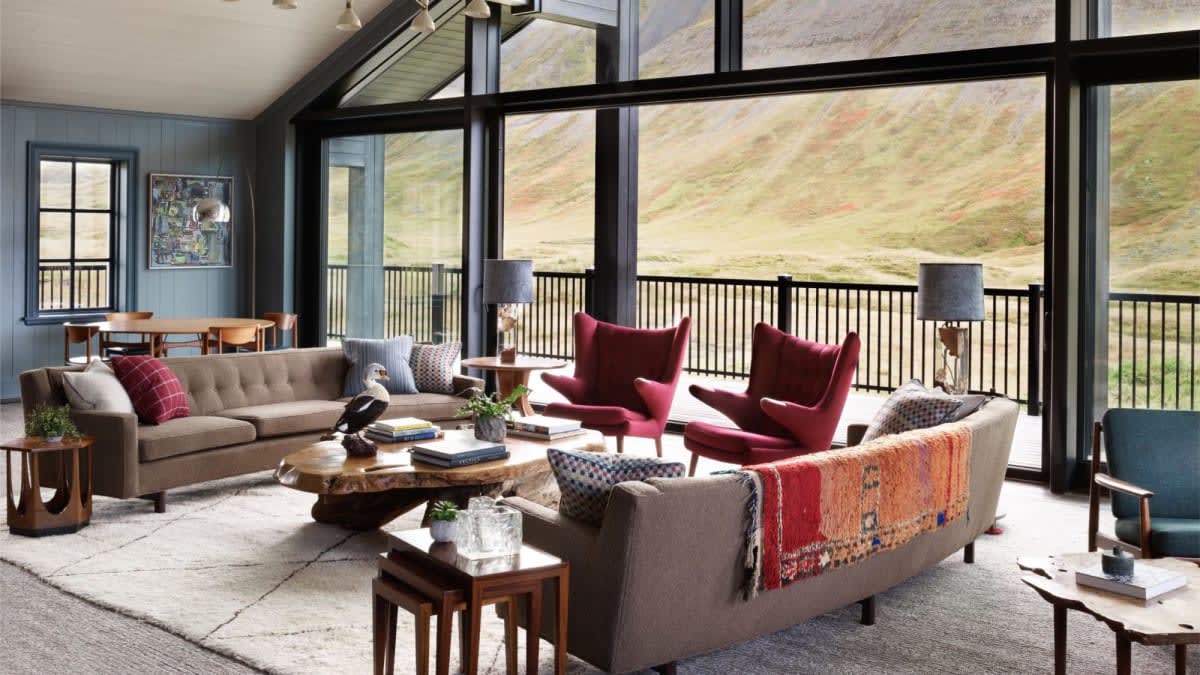
Searches for cool destinations rose by 74% year-on-year from the start of 2026, according to Trip.com data. For the months of June to August alone, searches for Norway, Iceland, Finland, Sweden and Denmark posted triple-digit growth.
Iceland stands out: flight searches surged 85% above last year. And the mirror effect arrived sooner than expected: Santorini and the Amalfi Coast recorded their first drop in bookings in a decade this summer.
The booking criterion nobody saw coming
Our summer coverage highlighted a more prosaic, and potentially more lasting, shift. During the June heatwaves, air conditioning became a standalone booking criterion, on a par with views or breakfast, acting as a filter applied by travellers even before checking prices.
For southern properties, this means a technical feature, long invisible in marketing pitches, has moved to the forefront of the product description.
What it costs, and who pays
This movement comes at a price, and it is not borne equally. For Nordic destinations, it means an extended season and rising rates, as Icelandic and Norwegian hotels were not built to absorb an extra twelve million visitors. For the Mediterranean, it represents the first fracture in a model built on guaranteed full summers.
The risk on that front is real: in July, we documented the impact of wildfires on southern French hospitality. A destination that burns doesn’t just lose a season, it loses its image, and an image takes longer to rebuild than a hotel.
A luxury hotel can buy marble. It cannot buy a housekeeper in three weeks.What the staff shortage reveals
The shortage is no longer about guests
This is the constraint least discussed, yet likely the most serious. 71% of hotels report vacancies they are unable to fill, and 65% of American properties face chronic shortages. The roles affected are hardly peripheral: housekeeping, front desk, food and beverage, maintenance, precisely those that create the luxury experience.
The response has primarily been financial: by March 2026, 70% of owners had increased pay to retain their teams, and 54% offered flexible hours. A luxury hotel can buy marble; it cannot buy a housekeeper in three weeks.
This is the friction point that could stall the preceding five trends. One can open a medical spa, sell residences and convert a brand, but people are still needed to maintain the standards promised by the brand.
Returning a star, the weak signal
One final movement, minor yet instructive because it runs counter to the other six. We reviewed a Périgord estate in September which, upon taking over management, voluntarily requested a downgrade from five to four stars, not to skimp on services, which remained unchanged, but to remove the symbolic barrier keeping locals at a distance.
nThe question the other trends avoid
An isolated case does not make a trend, and we will not claim it does. But it raises the question that the other six trends avoid: what use is a star rating when local clientele, those who fill country retreats mid-week, view it as a keep-out sign? If luxury growth stops relying solely on international travellers, this trade-off will be reconsidered.
- 📊 Market performance · CBRE, 2026 revenue per available room forecasts by segment.
- 🏠 Branded residences · Savills, 2025-2026 annual report · 764 programmes at end-2024, 910 at end-2025, over 1,500 expected by 2030.
- 🧖 Wellness and sleep · Global Wellness Institute for the size of wellness tourism · Grand View Research for the sleep market.
- 💷 Investment · Savills, EMEA hotel capital markets, data as of 30 June 2026.
- 🤖 Artificial intelligence · May 2026 industry survey · data published by Hilton on LightStay and pricing.
- 🧹 Employment · 2026 US industry surveys on unfilled positions and retention policies.
- 📚 Our survey · 704 news items published in French on La Revue des Hôtels between 1 March and 14 September 2026, categorised by theme based on titles and subheadings. It measures our coverage, not the entire market, and reflects a French perspective.
- 🗓️ Update · 14 September 2026.
- →Longevity tourism: seven exceptional European addresses where hotels become clinics
- →Sleep tourism: the trend of travelling to hotels for better sleep
- →Palace Merano: our full review of Italy’s premier medical spa
- →Coolcation 2026: the best cool destinations to spend the summer
- →The Middle East becomes the planet’s worst hotel market
- →We tested Domaine de Rochebois, its Nuxe spa and its dining overlooking the Dordogne valley