- 💷 The volume · £2.1bn of hotels sold in the UK between January and June 2026, nearly £500m more than in H1 2025, according to Savills.
- 🇪🇺 European market share · 24% of European volumes: the UK remains the continent’s leading hotel market for investors.
- 🏙️ London · £1.4bn, 69% of the national total, including £1.3bn in standalone assets, sold hotel by hotel rather than in portfolios.
- 🧾 Who is buying · Owner-operators (40%) and private equity funds (37%), which favour quality assets in markets with solid demand.
- 🏨 The regions · Crowne Plaza Marlow and Reading (around £80m for both), Courtyard by Marriott Oxford City Centre (£74m), hub by Premier Inn Edinburgh.
- 🔭 Outlook · Savills expects a second half of the year driven by prime assets, with one caveat: political and geopolitical risks could slow decisions in Q3.
The European hotel market has found its driving force. In the first half of 2026, £2.1bn worth of hotels changed ownership in the UK, according to Savills data, accounting for nearly a quarter of all capital invested on the continent. The figure rose by some £500m year-on-year, in an environment still marked by elevated interest rates and tight operating costs. Above all, it confirms a simple reading: capital is flowing towards quality assets that are well-located and well-operated, and London remains the benchmark address.
Contents
£2.1bn in six months: what the Savills figures reveal
The first quarter had already set the tone, with over £1.1bn exchanged, up 63% on the £680m recorded in Q1 2025. The second quarter maintained this pace, bringing the six-month total to £2.1bn. The UK’s share of European hotel investment stands at 24%, well ahead of its neighbours, at a time when several continental markets are seeing transaction volumes contract due to a lack of assets for sale.
| Invested volume | £2.1bn |
| Year-on-year change | Around +£500m |
| Share of Europe | 24% |
| London | £1.4bn, 69% of total |
| Standalone assets in London | £1.3bn |
| Owner-operators | 40% of acquisitions |
| Private equity | 37% of acquisitions |
| First quarter | £1.1bn, +63% year-on-year |
London captures £1.4bn, asset by asset
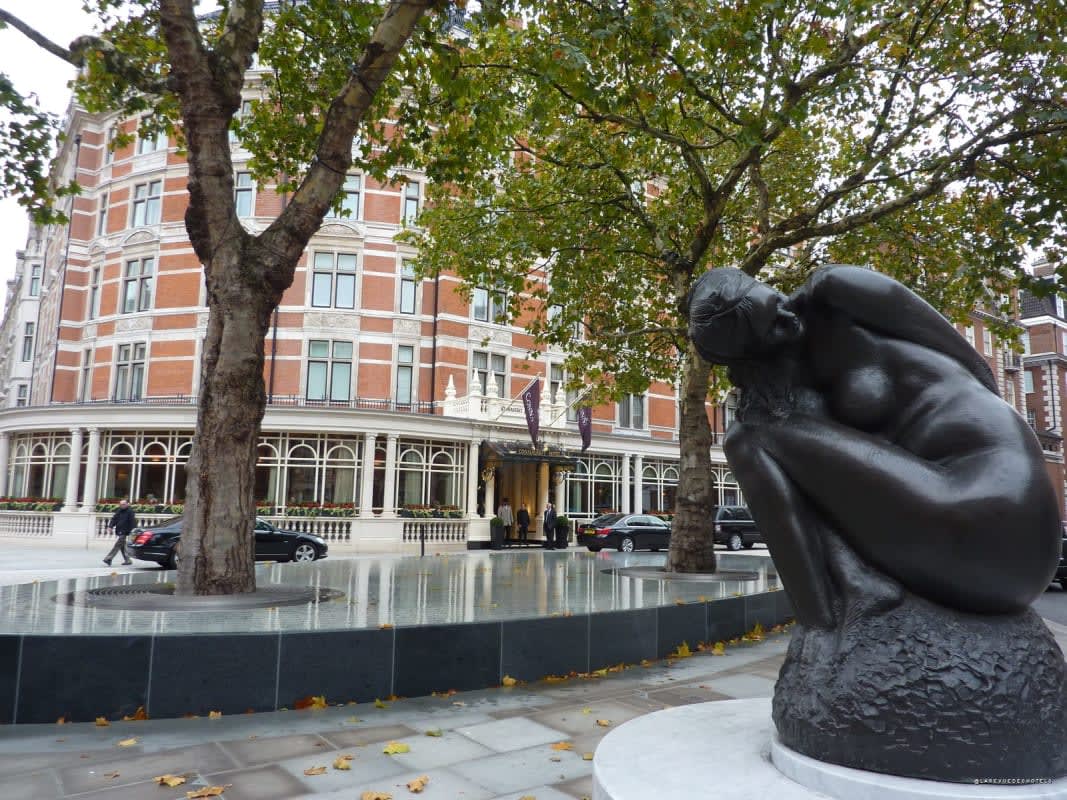
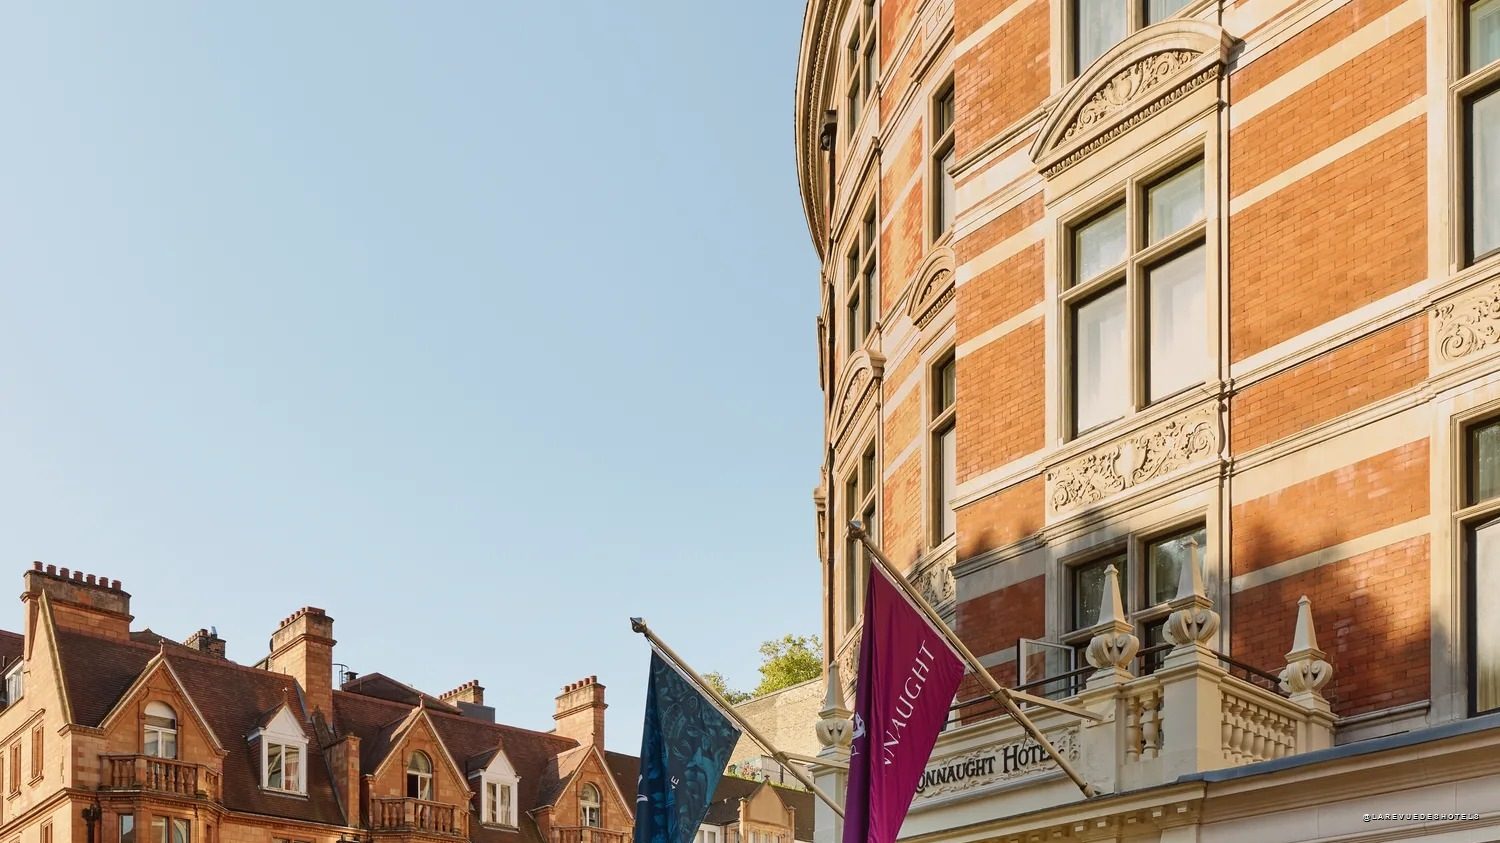
The capital absorbed £1.4bn, representing 69% of the national total. The breakdown is telling: £1.3bn of these London transactions involved standalone assets, purchased one hotel at a time rather than in portfolios. Buyers want to choose their specific address, neighbourhood and operator, and are willing to pay for this privilege. Mayfair, Belgravia, Knightsbridge and, more recently, the City and Shoreditch concentrated the bulk of the demand, driven by record occupancy rates and average room rates that have never been higher.
This preference for single assets is also explained by the scarcity of supply. London builds few luxury hotels, and major projects, such as the conversion of Admiralty Arch into a Waldorf Astoria, take years. Acquiring an existing hotel remains the fastest way to gain exposure to record-breaking tourist demand, with the 2026 season shaping up to be the strongest since the pandemic.
Who is buying: operators first, funds second
Two profiles dominated the half-year. Owner-operators, who own and run their hotels, accounted for 40% of acquisitions, a sign of their belief in the value of their operational expertise in a market where performance makes all the difference. Private equity funds followed with 37%, often targeting repositioning plays where renovation or rebranding can create value within a few years. Institutional investors and sovereign wealth funds completed the picture, being more selective and focusing on prime London trophies.
David Kellett, head of EMEA hotel capital markets at Savills, summarises the mindset of buyers: capital is available “for the right assets, in locations backed by robust demand drivers”. He believes that the strength of operating fundamentals and the depth of available capital justify a positive outlook for the market’s prime assets.
Outside London: Marlow, Reading, Oxford and Edinburgh
The regions were equally active, with several landmark transactions. On 20 April 2026, Millemont Capital Partners finalised the acquisition of the Crowne Plaza Marlow (168 rooms) and the Crowne Plaza Reading (174 rooms), two Thames Valley hotels sold by Meridian Leisure Hotels for an estimated £80m. On 22 June, the same buyer signed the largest regional urban transaction of the year outside London: the Courtyard by Marriott Oxford City Centre, featuring 169 rooms opened in 2019 and an occupancy rate consistently above 90%, acquired for £74m from Dominus, which had bought the site in 2014. Ashley Shaw, managing director of Millemont, highlights the blend of tourist, university and corporate demand that makes Oxford one of the country’s most sought-after markets.
In Scotland, a hub by Premier Inn in Edinburgh also changed hands, illustrating investor appetite for compact, budget-friendly hospitality in regional capitals. Alongside these standalone assets, midscale branded portfolios continued to change hands, such as the seven Novotel and ibis hotels acquired by Starboard and LaSalle earlier this year.
Second half: solid fundamentals, geopolitical caution
Savills anticipates a second half of the year supported by deep capital pools and constrained room supply in major cities. The firm nevertheless adds a caveat: political and geopolitical risks could weigh on investor decisions in the third quarter. The best-positioned assets and top-performing regional markets, such as Oxford, Edinburgh, Bath and Cambridge, are expected to continue attracting buyers, while ageing hotels lacking renovation programmes will prove harder to sell.
Our perspective
These £2.1bn speak less of euphoria and more of careful selection. Buyers are no longer betting on the UK market as a whole, but on specific hotels, in specific cities, with specific operators. This is good news for addresses that invest in their product, and a warning for the rest. For the traveller, this trend is already visible in the wave of renovations stretching from Marlow to Oxford, and in a capital where every change of ownership is now accompanied by an upscale repositioning.